Willingness to contribute is not always enough: from civic awareness to action
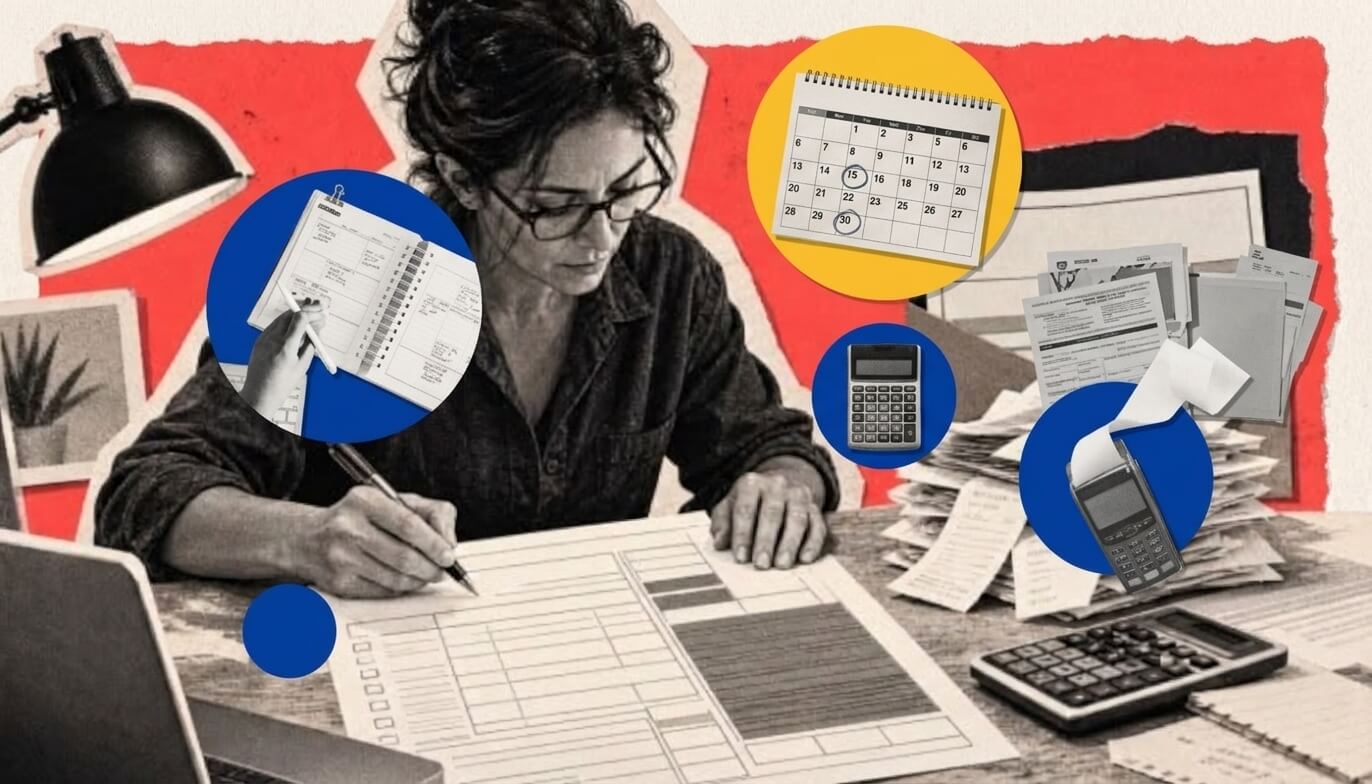
“I’ll do it tonight.”
Let us imagine Laura, a self-employed professional who has just received a notice about filing her tax return. She knows she has to do it and intends to comply. She also recognizes the importance of taxes in funding public services.
She opens the message on her cell phone between meetings. She finds several paragraphs containing regulatory references and a link. She decides to save it for when she has time to read it carefully.
When she gets home that night, tired, she forgets to complete the filing. Over the weekend, while chatting with a friend, she remembers it and tries to complete it, but a question arises, so she puts it off.
The deadline passed, and Laura did not file her tax return on time.
Did she lack information? Organization? Help?
Using this hypothetical scenario, we in the tax administration can address an important question: What happens between the intention to comply and the act of complying?
In the 2020 blog post, Conscience, Morality, and Fiscal Discipline: Their Role in Tax Compliance, Dario González reflected on the factors that drive compliance. I am revisiting that question from the perspective of civic awareness and its relationship to our everyday decisions.
Civic awareness, in the tax context, allows us to connect our contributions with the financing of collective needs. It also involves taking an interest in how resources are used, demanding transparency, and participating in public affairs.
This aspect is important because tax compliance involves perceptions of fairness, trust, and shared responsibility. Various publications by CIAT and the OECD have addressed concepts such as tax morality and tax culture, as well as their relationship to trust and institutions. However, understanding why contributing matters is not always enough to actually do it.
Let us go back to Laura: she may be convinced of her responsibility and yet still put off completing the process. Between her willingness and her actual compliance, other factors come into play: the time available, the clarity of the instructions, the ease of the procedure, and the opportunity to have her questions answered.
It is in this area that the behavioral sciences offer a useful perspective, since they study how we make decisions and act, considering factors such as limited attention, the tendency to procrastinate, habits, and the influence of context.
Their application in tax administrations allows us to examine how communications and procedures can facilitate or hinder compliance.
With this new perspective, I invite you to expand on the questions we asked ourselves at the beginning of the story: Did Laura understand what she was supposed to do? Did she identify the due date? Was she able to find the procedure easily? At which step did she get stuck?
Civic awareness helps us understand why paying taxes matters. Behavioral science allows us to explore what makes it easier or harder to put that intention into practice.
Of course, let us not forget that there are economic challenges, barriers to access, and deliberate decisions that require different responses; that is why it is important to realize that
Understanding where the obstacle lies will help us choose an appropriate response.
For tax authorities, this approach presents a practical opportunity: to observe the steps a person must take to comply. However, we must not forget to exercise caution in this process: using accurate information, respecting the taxpayer’s rights, and facilitating informed decisions. Trust is at stake in every interaction.
We do not know what would have happened if Laura had received another communication that would have allowed her to identify these three key elements: what she needs to do, by when, and how to access the process. That is precisely why it is important to observe, ask questions, and evaluate before attributing her failure to comply corresponds to a lack of commitment.
I will leave you with one final thought: in addition to explaining why it is important to contribute, are we always making easier for our taxpayers to comply? And have we confirmed this with taxpayers themselves?
49 total views, 7 views today