DT-06-2026: Building Accounting Evidence in Tax Audits: International Standards, Substance Over Form, and Digital Challenges in Latin America
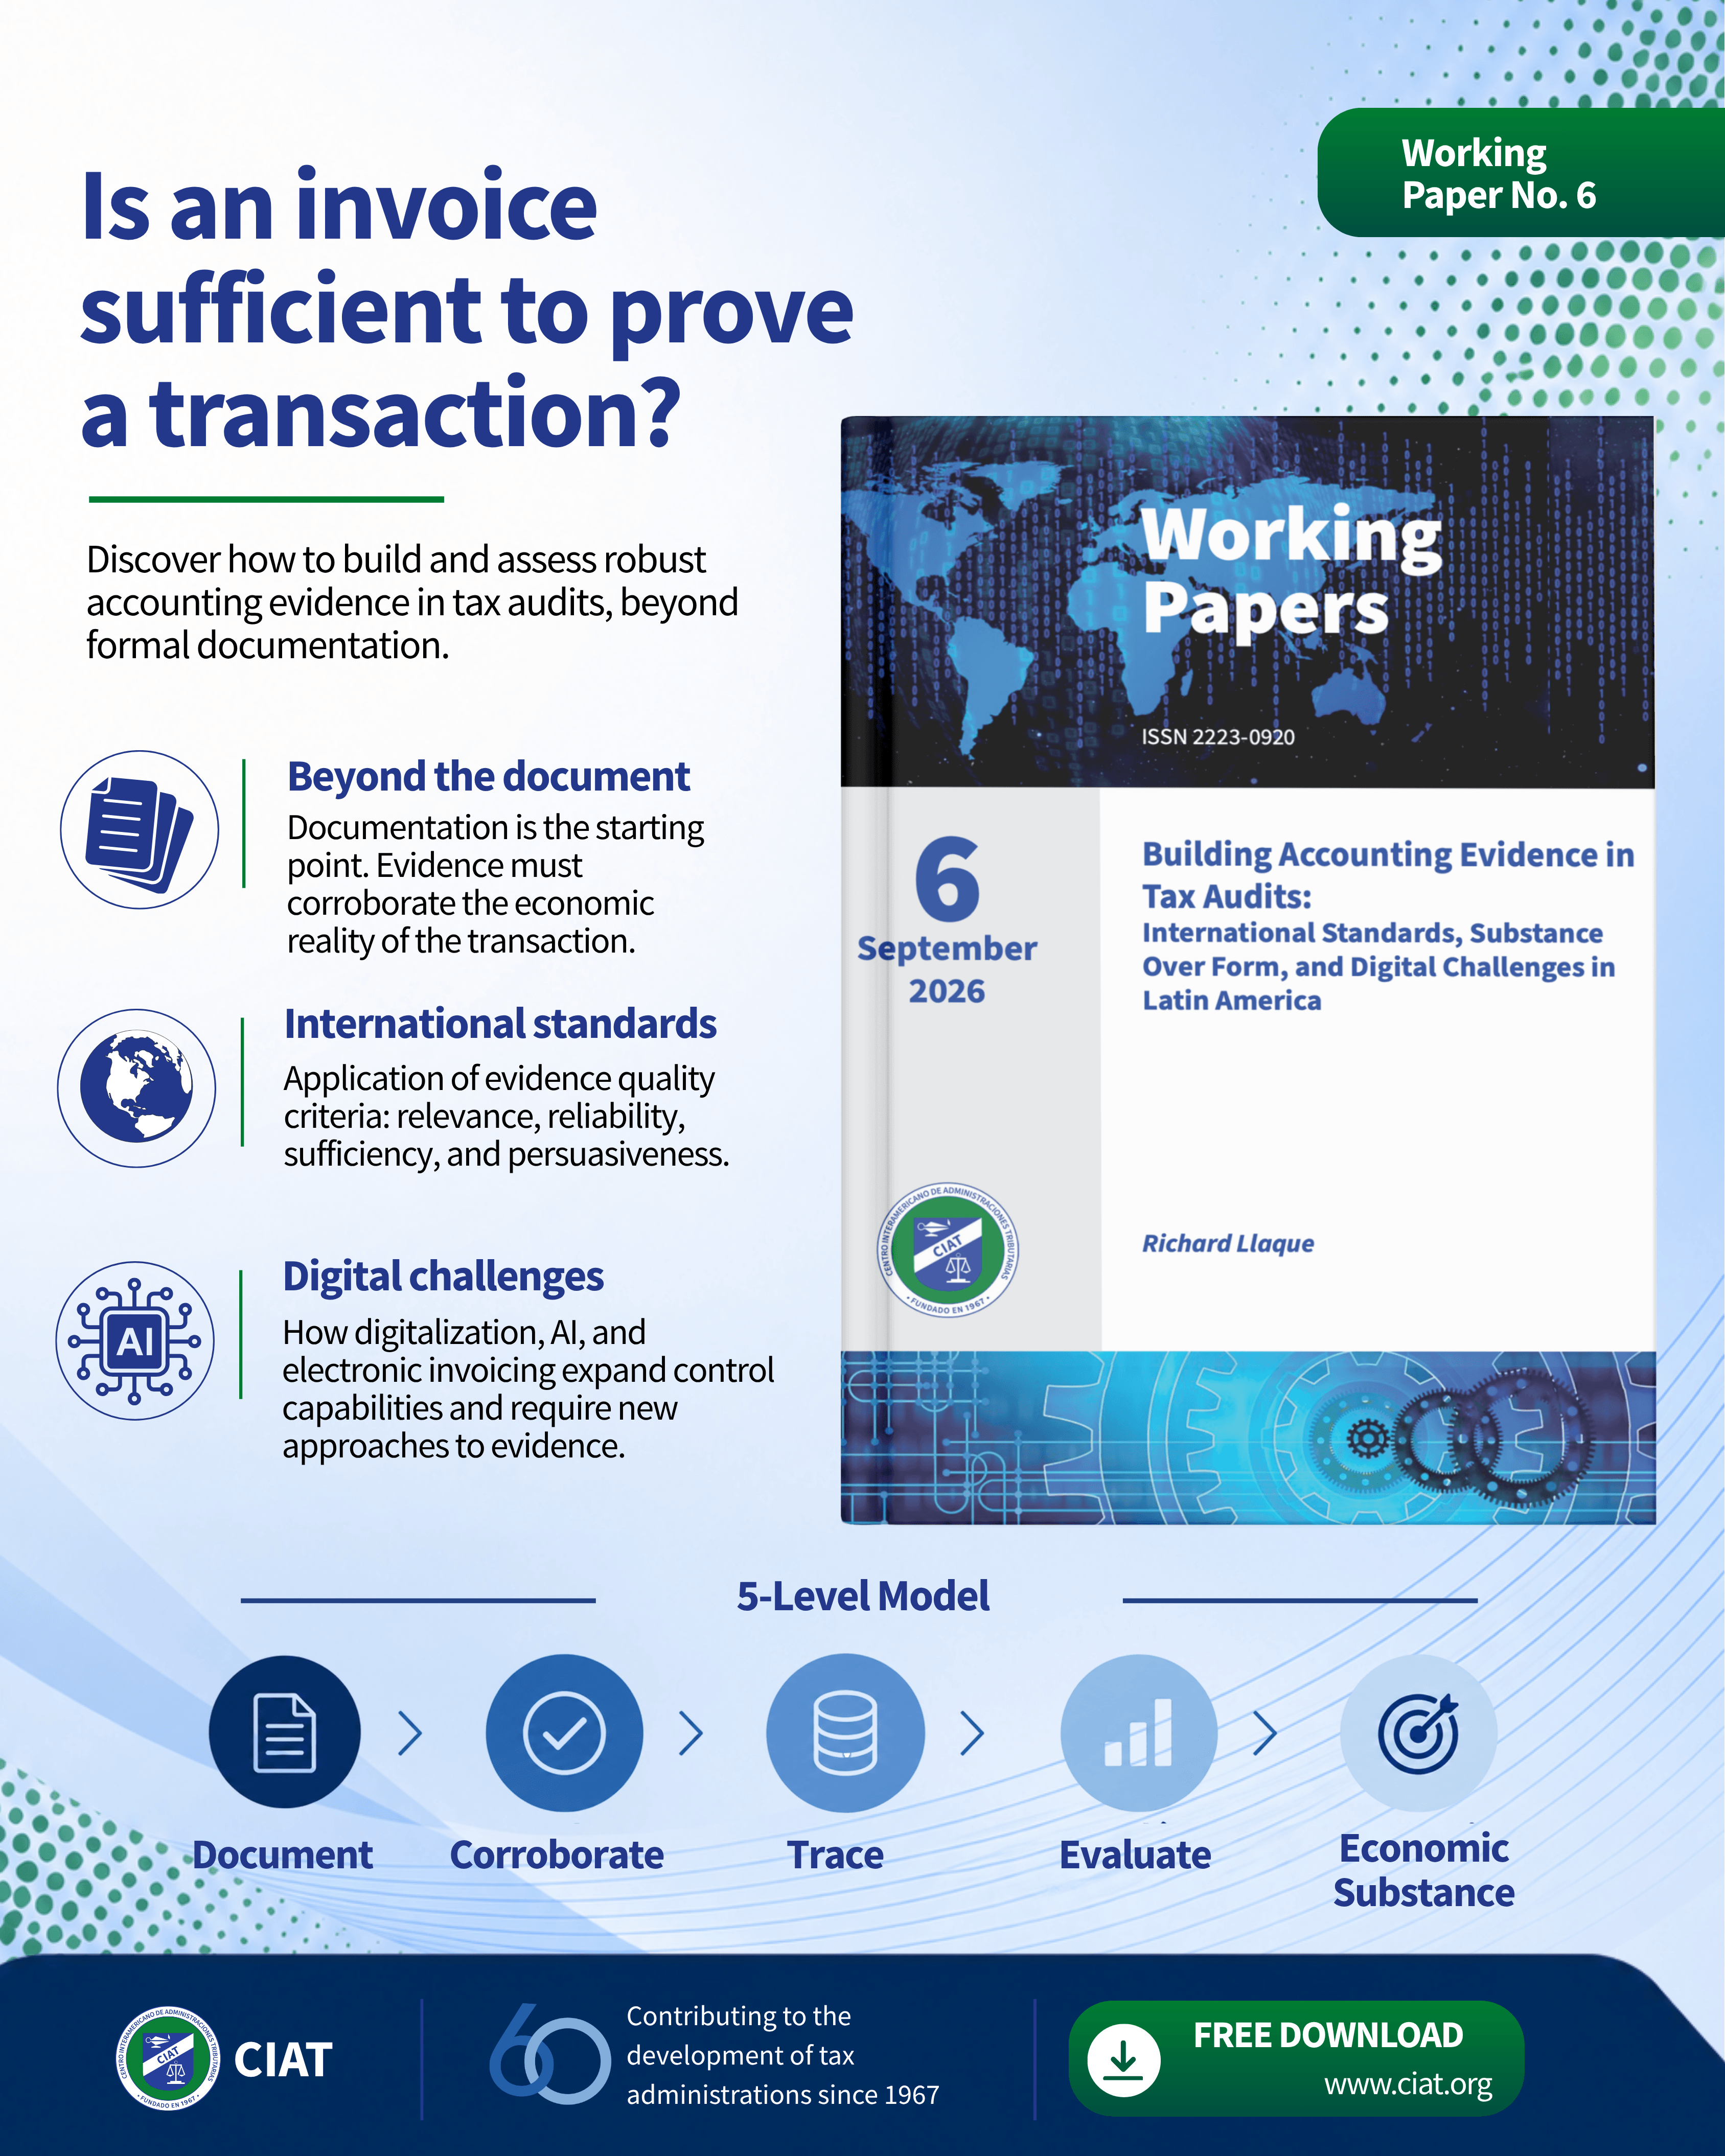 This document examines the theoretical, regulatory, and technological foundations that underpin accounting evidence in the field of tax auditing, considering international auditing standards, evidentiary quality, professional skepticism, the substance-over-form principle, and the challenges arising from digital transformation.
It also presents a model structured in five successive levels for developing accounting evidence, designed as a conceptual framework that can be adapted to the region’s various legal systems. The study also assesses the impact of digitalization and artificial intelligence (AI) on the collection and evaluation of tax evidence.
42 total views, 42 views today